Service
Tronc HMRC Compliance Review
Independent compliance review of your tronc scheme against HMRC guidance and the Tips Act duties in force since 1 October 2024.
Tronc HMRC compliance is narrower than general tax compliance. It comes down to two sets of rules: HMRC's E24 guidance, which decides whether tronc payments are free of National Insurance, and the Employment (Allocation of Tips) Act 2023, which decides whether tips are handled fairly and transparently. We review your arrangement against both and give you a written list of what to fix. We do not handle general VAT returns, corporation tax or tax investigations.
What HMRC looks at in a tronc
- Who decides the split. E24 asks whether the troncmaster allocates without direction from the employer. A manager "suggesting" shares, or an owner approving the spreadsheet, is the usual failure.
- Whether payments are really voluntary. Tips customers choose to leave, and service charge that is genuinely discretionary, can qualify. A mandatory service charge paid to staff attracts NIC whichever route it takes.
- Whether pay is promised. If contracts or offer letters treat tronc as part of guaranteed pay, the payments look like wages.
- Whether PAYE is operated. Income tax is always due on tronc payments, through a tronc PAYE scheme or through your payroll on the troncmaster's figures.
- Whether the money stays in the tronc. Funds used to top up the minimum wage, cover breakages or pay card fees beyond what the law allows are a problem.
What the Tips Act adds
Since 1 October 2024 employers must pass on all qualifying tips to workers without deductions (other than tax and National Insurance), allocate them fairly having regard to the statutory Code of Practice, pay them by the end of the month after they were received, have a written tipping policy available to workers, and keep records for three years. These duties apply whether or not you use a tronc, and meeting them does not by itself make a tronc NIC-free.
How the review works
Document request.
Your tronc rules, tipping policy, a sample of contracts, payslips, three to twelve months of distribution records and the till or card reports behind them.
Conversations.
Short calls with whoever really runs the tronc, payroll and one site manager, because practice often differs from the document.
Testing.
We trace money from receipt to payslip for sample periods, check who made each allocation decision, and separate voluntary amounts from any mandatory charge.
Written findings.
Each gap is described, ranked by risk, and paired with the specific change needed: wording, process, or who holds the role.
Deliverables
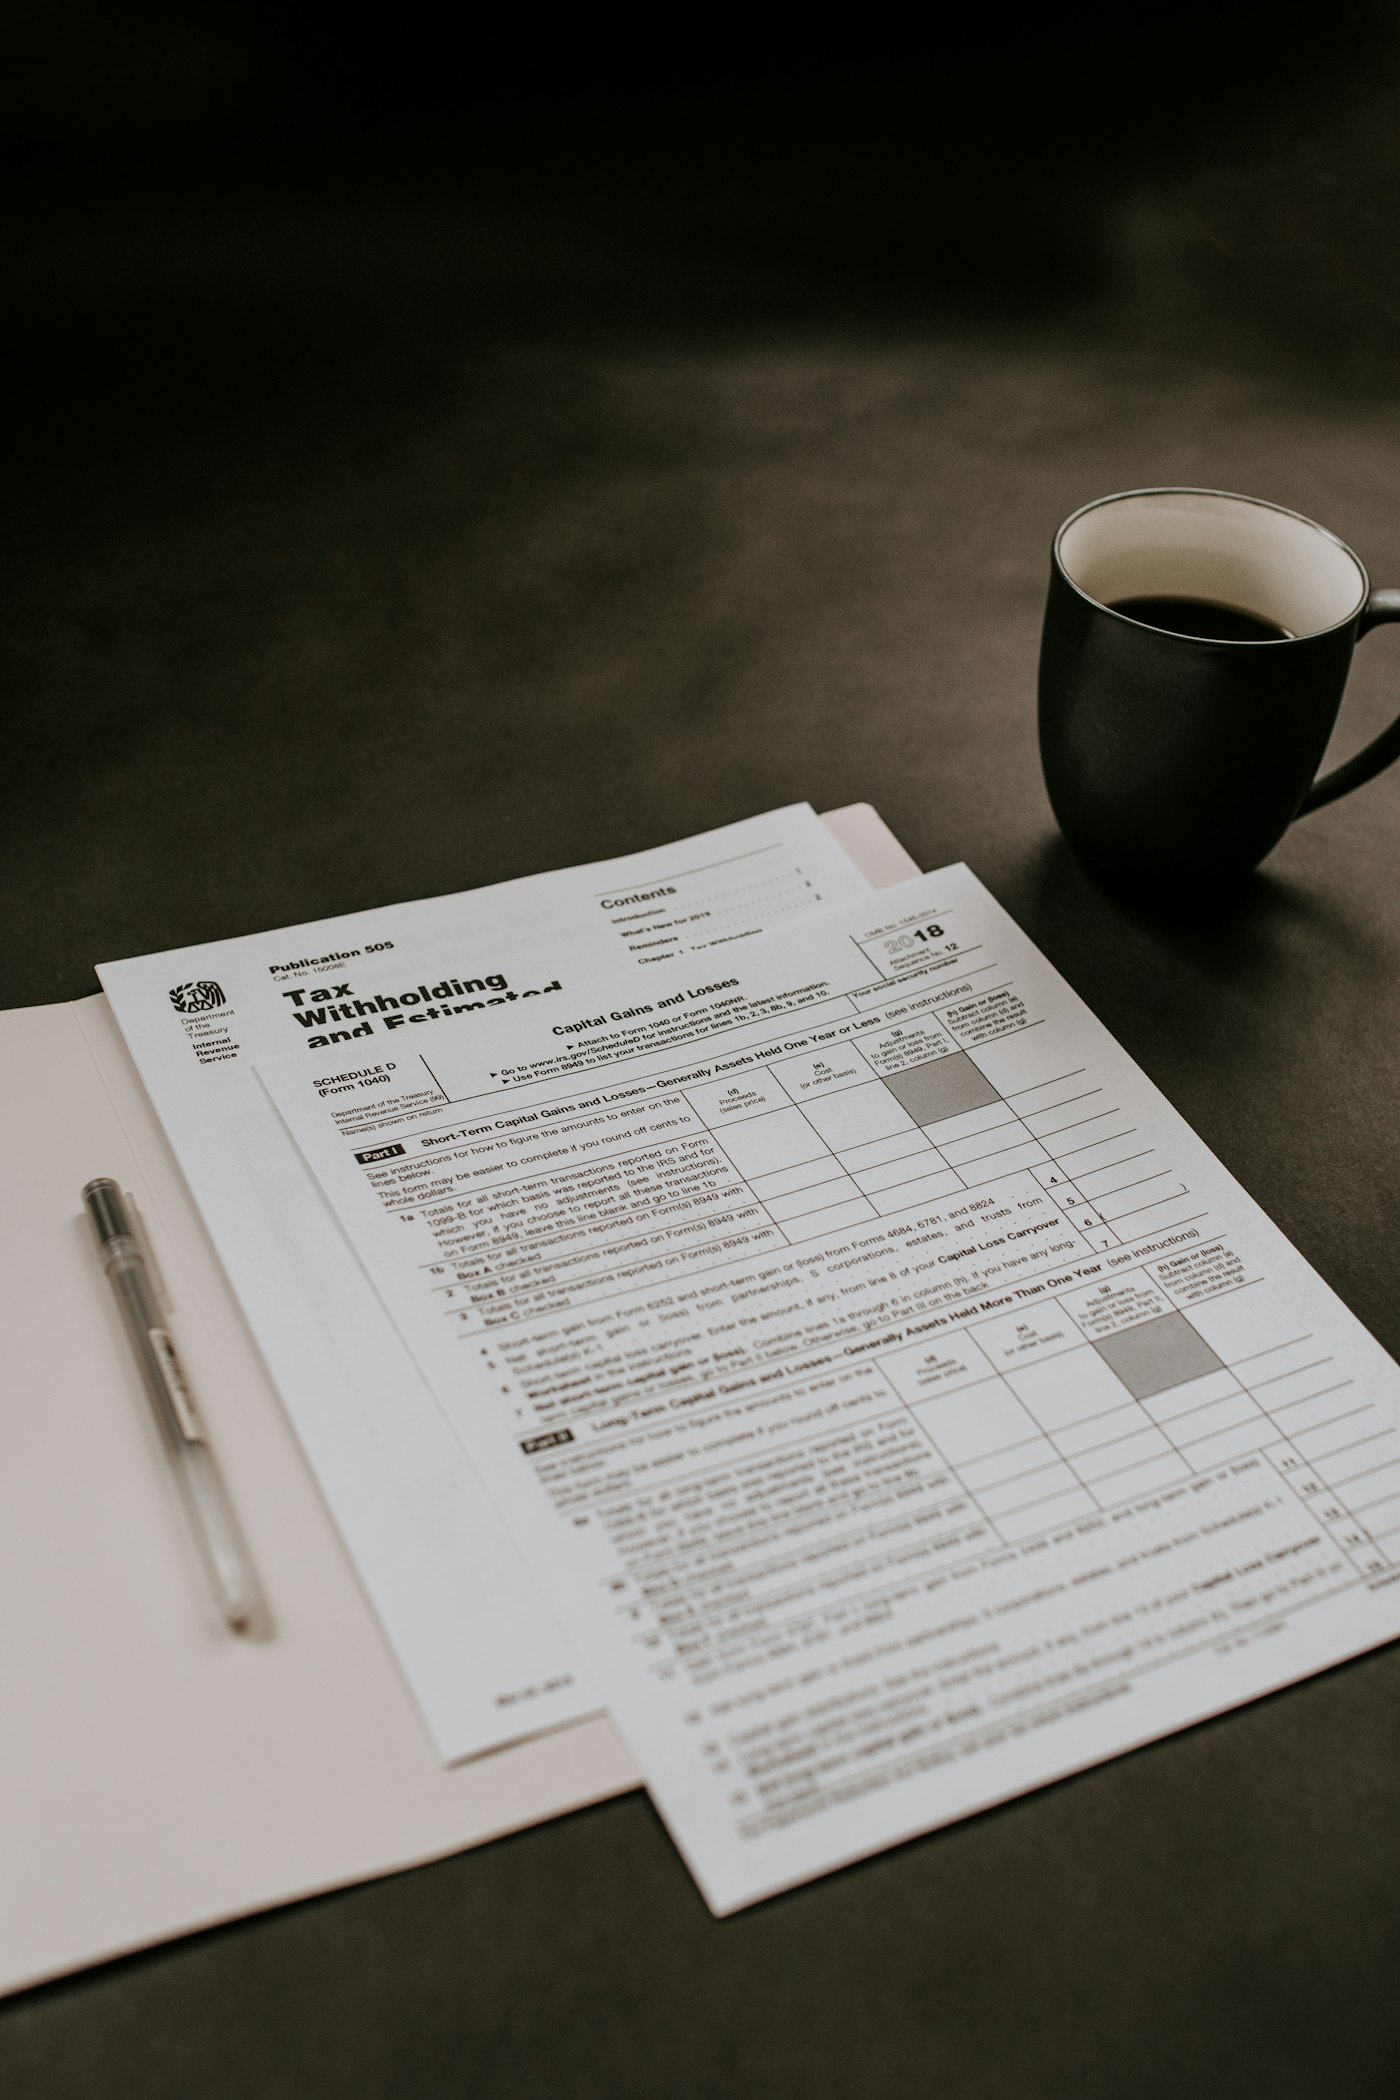
- A written gap list against E24 and the Tips Act, ranked by risk
- An estimate of employer NIC exposure if past distributions were treated as wages, so you can judge priority
- Draft corrections to rules, policy and contract wording
- A records checklist that answers a worker information request
Typical situations
- A group that grew site by site, with each general manager running tips their own way.
- A change of payroll provider that quietly merged tronc into ordinary pay.
- A staff complaint about how shares are worked out, where you need to know your position first.
- An acquisition, where the buyer wants to know what liability comes with the tronc.
After the review
Most fixes are practical rather than legal: moving the allocation decision away from site managers, rewriting a contract clause, separating a mandatory service charge from voluntary tips in the till, or setting a payment date that meets the monthly deadline. You can make the changes yourself, ask your current troncmaster to, or have us implement them. Where the role of troncmaster itself is the problem, we can act as independent troncmaster going forward.
Limitations
HMRC does not approve tronc schemes in advance, and no adviser can give you an HMRC sign-off. The review tells you how your arrangement compares with published guidance and what to change. Where past exposure looks material, we will recommend you take formal advice on disclosure; we will not guess on your behalf.
What affects the fee
Fees depend on the number of venues and employing entities, the number of periods we test, the state of your records, and whether you want us to implement the fixes or hand them to your current troncmaster. We confirm scope and fee after a free scoping call.
For a quick first read, try the free tronc health check. For a formal evidence-based report, see the independent tronc audit, or request a scoping call.
Official guidance we work from
- HMRC E24: tips, gratuities, service charges and troncs
- Distributing tips fairly: statutory Code of Practice
- GOV.UK: employee gets tips through a tronc
This page is general information, not tax or legal advice for your business. Outcomes depend on how your arrangement actually runs.
What happens when you start
Days 1–7: document review
We collect your tronc rules, contracts, payslip samples and distribution records and check them against current HMRC guidance (E24) and the Employment (Allocation of Tips) Act 2023.
Days 8–20: findings
You receive a written report ranking each gap by NIC exposure, with the specific wording or process change needed to close it.
Days 21–30: remediation
We implement the fixes — revised rules, corrected payslip treatment, a written tips policy and the record-keeping routine the Act requires.
Who this is not for
Tronc HMRC Compliance Review only works when these conditions hold. We would rather say so now.
- Businesses that do not take card tips or service charge — there is nothing for a tronc to distribute.
- Employers who want to keep control of who gets what: an independent troncmaster must allocate free of employer direction, or the NIC exemption fails.
- Anyone expecting NIC relief on a mandatory service charge. Under HMRC E24, a mandatory charge paid to staff attracts NIC however it is shared.
- Businesses looking for a compliance sign-off without changing how allocation decisions are made.
Card tips, discretionary service charge and multi-site groups are all in scope.
Frequently Asked Questions
Related tronc services
Get in touch
Talk to a Tronc Expert
Free 30-minute call to review your tips, service charges and HMRC exposure — with specific advice on Tronc HMRC Compliance Review.
- +44 207 183 3436
- info@troncmasterservices.co.uk
- United Kingdom · Serving all UK hospitality